Real Estate Market Trends 2026: Housing Affordability Analysis
Anúncios
The real estate market is a dynamic ecosystem, constantly evolving under the influence of myriad economic, social, and political forces. As we cast our gaze towards 2026, understanding the trajectory of housing affordability 2026 becomes paramount for prospective homeowners, investors, policymakers, and industry professionals alike. This comprehensive analysis will dissect the key trends, economic indicators, and potential disruptors that are expected to shape the housing landscape in the coming years, with a particular focus on the ever-critical issue of affordability.
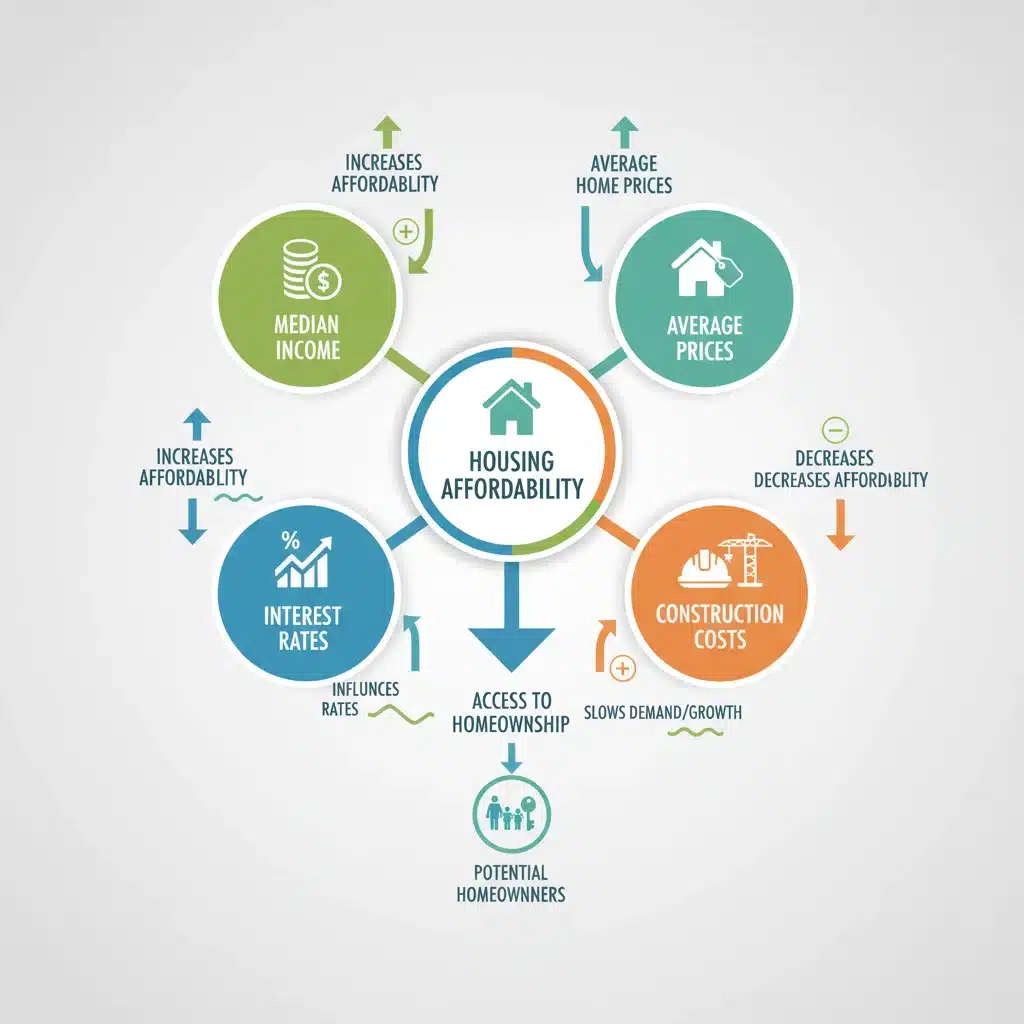
The concept of housing affordability is not merely about the price tag of a home; it encompasses a complex interplay of income levels, interest rates, lending standards, supply and demand dynamics, and government policies. A house might be nominally cheaper in one region, but if local wages are disproportionately low, it remains unaffordable. Conversely, a higher-priced home in a high-income area might still be considered affordable. Therefore, our exploration of housing affordability 2026 will adopt a holistic perspective, considering these intricate relationships.
Anúncios
Forecasting the future of real estate is an art as much as it is a science. While no one possesses a crystal ball, robust economic modeling, historical data analysis, and an understanding of current geopolitical and technological shifts allow us to make informed projections. This article aims to provide a clear, data-driven outlook on what to expect as we approach the mid-point of the decade, specifically concerning the accessibility of housing for the average citizen.
Anúncios
The Current State of Play: A Precursor to 2026
To understand where we are headed, we must first acknowledge our starting point. The years leading up to 2026 have been characterized by significant volatility in the global economy. Inflationary pressures, supply chain disruptions, geopolitical conflicts, and the lingering effects of the recent pandemic have all left indelible marks on the housing market. Interest rates, after an extended period of historic lows, have seen significant increases, directly impacting borrowing costs and, consequently, housing affordability 2026.
Many markets have experienced unprecedented price growth, fueled by strong demand, limited inventory, and favorable borrowing conditions. However, as interest rates climbed, the pace of appreciation has slowed, and some markets have even seen modest corrections. This cooling period, while potentially easing some of the pressure on buyers, has also introduced uncertainty. The labor market, while generally robust in many developed nations, faces its own set of challenges, including wage stagnation for some segments of the population and the rise of the gig economy, which can complicate mortgage qualification.
The demographic landscape is also shifting. Millennials, now in their prime home-buying years, face significant hurdles in entering the market, often burdened by student loan debt and higher living costs. Generation Z is beginning to enter the workforce, bringing their own unique preferences and financial realities. These generational shifts, coupled with ongoing urbanization trends and the increasing desire for remote work flexibility, will undoubtedly influence demand patterns and the types of housing most sought after.
Moreover, the construction industry has grappled with labor shortages, rising material costs, and regulatory hurdles, all contributing to a persistent undersupply of housing in many desirable areas. This supply-demand imbalance is a fundamental driver of price escalation and a major impediment to improving housing affordability 2026.
Economic Indicators Shaping Housing Affordability 2026
Several key economic indicators will play a pivotal role in determining the state of housing affordability in 2026. Monitoring these factors will be crucial for anyone looking to navigate the market successfully.
Interest Rates and Monetary Policy
Central banks’ decisions on interest rates are perhaps the single most influential factor affecting mortgage affordability. Higher interest rates translate to higher monthly mortgage payments, reducing purchasing power. If inflation remains stubbornly high, central banks may continue their hawkish stance, keeping rates elevated. Conversely, a significant economic downturn could prompt rate cuts, providing some relief to borrowers. The trajectory of inflation and the corresponding monetary policy responses will be critical in shaping housing affordability 2026.
Inflation and Wage Growth
While inflation directly impacts the cost of living, its relationship with wage growth is vital for affordability. If wages keep pace with or outstrip inflation, real incomes rise, improving purchasing power. However, if inflation outpaces wage growth, as has been the case in many regions recently, the average household’s ability to afford housing diminishes. Understanding the delicate balance between these two forces will be key to forecasting housing affordability 2026.
Unemployment Rates and Economic Stability
A strong and stable job market is foundational to a healthy housing market. Low unemployment rates generally indicate economic prosperity, consumer confidence, and a greater ability for individuals to secure and maintain mortgage payments. Conversely, rising unemployment can lead to foreclosures and a softening of demand. The overall stability and growth of the global and local economies will therefore be a significant determinant of housing affordability 2026.
Housing Supply and Construction Costs
The fundamental economic principle of supply and demand applies acutely to housing. A persistent shortage of housing units, particularly in high-demand areas, inevitably drives up prices. Factors contributing to supply constraints include restrictive zoning laws, lack of developable land, labor shortages in construction, and the soaring cost of building materials. Government initiatives to streamline permitting processes, incentivize affordable housing development, and invest in infrastructure could help alleviate these pressures and improve housing affordability 2026. The cost of construction, influenced by everything from lumber prices to regulatory fees, directly impacts the final price of new homes.
Demographic Shifts and Their Impact on Housing Affordability 2026
Demographics are not destiny, but they certainly shape market trends. Several significant demographic shifts will influence housing affordability 2026.
Millennials and Generation Z
As mentioned, Millennials are a dominant force in the housing market. Many are now forming families and seeking more permanent housing solutions. However, their entry into homeownership has been delayed compared to previous generations due to economic headwinds. Generation Z, while younger, will increasingly enter the market, bringing their own demands for sustainable, tech-integrated, and flexible living spaces. Their combined purchasing power and preferences will significantly influence demand and pricing.
Urbanization vs. Suburbanization/Ruralization
The pandemic prompted a temporary exodus from dense urban centers, as remote work became widespread. While some of this trend has reversed, a hybrid work model appears to be here to stay for many industries. This could continue to fuel demand in suburban and even rural areas, potentially spreading affordability challenges beyond traditional urban cores. The balance between urban revitalization and the continued appeal of less dense areas will be a key dynamic in housing affordability 2026.
Aging Population and Downsizing
Many developed nations face an aging population. As Baby Boomers and older generations look to downsize or relocate in retirement, this could free up larger family homes, potentially increasing supply in certain segments of the market. However, it also creates demand for accessible, smaller, and often more community-oriented housing options, which may not always be readily available or affordable. The impact of this demographic on both supply and specific types of demand will be crucial for housing affordability 2026.
Policy Interventions and Their Role in Housing Affordability 2026
Government policies at local, state, and national levels play a critical role in shaping the housing market and, by extension, affordability. These interventions can either exacerbate or alleviate the challenges.
Zoning and Land Use Regulations
Restrictive zoning laws, such as those mandating large minimum lot sizes or prohibiting multi-family dwellings, limit housing density and increase costs. Reforms aimed at promoting denser development, mixed-use zoning, and streamlined permitting processes could significantly boost housing supply and improve housing affordability 2026. Many cities are grappling with how to balance community character with the urgent need for more housing.
Affordable Housing Initiatives
Direct government subsidies, tax incentives for developers building affordable units, and rent control measures are all tools used to address affordability. The effectiveness and political feasibility of these initiatives vary widely. As we approach 2026, expect continued debate and experimentation with different policy approaches to make housing more accessible for lower and middle-income households.
Mortgage Lending Standards and First-Time Buyer Programs
Lending standards, including down payment requirements and debt-to-income ratios, directly influence who can qualify for a mortgage. While responsible lending is crucial to prevent another housing crisis, overly stringent standards can shut out creditworthy buyers. Government-backed loan programs and first-time buyer assistance initiatives can help bridge the gap, but their scope and funding will be important factors in housing affordability 2026.
Tax Policies
Property taxes, capital gains taxes on real estate, and deductions for mortgage interest all have an impact on housing costs and investment decisions. Changes to these tax policies could significantly alter the economics of homeownership and rental property investment, thereby affecting housing affordability 2026.
Technological Advancements and Their Potential Influence
Technology is a constant disruptor, and the real estate sector is no exception. Innovations could offer solutions to some of the persistent affordability challenges.
Construction Technology
Advances in construction techniques, such as modular housing, 3D printing of homes, and prefabrication, have the potential to significantly reduce construction timelines and costs. If these technologies become more widespread and scalable, they could alleviate supply shortages and contribute to more affordable housing options. The adoption rate of these innovations will be a factor in housing affordability 2026.
PropTech and Data Analytics
Property technology (PropTech) platforms are making real estate transactions more transparent and efficient. Advanced data analytics can provide deeper insights into market trends, helping developers build where housing is most needed and allowing buyers to make more informed decisions. While these tools primarily optimize existing processes, their broader impact on market efficiency could indirectly support housing affordability 2026 by reducing transactional costs and improving resource allocation.
Smart Home Technology and Energy Efficiency
While not directly related to initial purchase price, smart home technology and energy-efficient building practices can reduce long-term ownership costs, making housing more affordable over its lifespan. As energy costs remain a concern, the demand for such features will likely grow, potentially influencing the value and appeal of homes built with these considerations.
Regional Variations in Housing Affordability 2026
It is crucial to remember that the real estate market is highly localized. Trends and challenges in housing affordability 2026 will vary significantly from one region to another, even within the same country.
High-Cost Coastal Cities
Major coastal cities, often characterized by strong job markets, limited land, and restrictive zoning, are likely to continue facing severe affordability challenges. While some may see price corrections, the underlying supply-demand imbalance and high demand for urban living will likely keep prices elevated.
Emerging Markets and Secondary Cities
Secondary cities and emerging markets, particularly those with growing tech sectors or expanding industries, could see continued appreciation as people seek more affordable alternatives to primary urban centers. However, this growth could also lead to new affordability pressures in these previously less expensive areas.
Rural and Remote Areas
Remote work has opened up possibilities for living in rural or more remote areas, where housing costs are traditionally lower. This trend could continue to boost demand in these regions, though infrastructure limitations and access to amenities may cap their growth. The extent to which remote work persists will be a key factor in housing affordability 2026 in these locales.
The Role of Investment and Institutional Buyers
The increasing presence of institutional investors in the housing market, particularly in the single-family rental sector, has been a topic of debate. These buyers often have significant capital and can outcompete individual homeowners, especially in certain price ranges. The extent of their continued involvement and any potential regulatory responses to it will influence supply dynamics and housing affordability 2026.
For individual investors, the changing interest rate environment and market dynamics will require careful consideration. Yields on rental properties may be squeezed by higher borrowing costs, while the potential for significant capital appreciation may be more subdued than in recent years. This could lead to a re-evaluation of investment strategies and a potential shift in the balance of buyers in the market.
Strategies for Navigating Housing Affordability 2026
For prospective homeowners, understanding the landscape of housing affordability 2026 is the first step towards a successful purchase. Here are some strategies:
- Financial Preparedness: Focus on improving credit scores, reducing debt, and saving for a substantial down payment. The higher interest rate environment makes strong financial health even more critical.
- Explore First-Time Buyer Programs: Research and leverage any local, state, or federal programs designed to assist first-time homebuyers with down payment assistance or favorable loan terms.
- Consider Alternative Housing Options: Look beyond traditional single-family homes. Condominiums, townhouses, and even multi-family properties (where you live in one unit and rent out others) can offer more affordable entry points into homeownership.
- Geographic Flexibility: Be open to considering homes in secondary cities, suburbs, or even rural areas that offer better value, especially if remote work is an option.
- Patience and Persistence: The market may remain challenging, requiring patience. Stay informed, be ready to act when opportunities arise, and don’t be discouraged by initial setbacks.
- Professional Guidance: Work with experienced real estate agents and mortgage brokers who understand the local market nuances and can guide you through the complexities of the buying process.
For policymakers, the challenge of housing affordability 2026 requires a multi-faceted approach. This includes:
- Supply-Side Solutions: Reforming zoning laws, incentivizing diverse housing types, and investing in infrastructure to support new development.
- Demand-Side Support: Targeted assistance programs for vulnerable populations, alongside careful consideration of broad-based subsidies that could inadvertently inflate prices.
- Economic Stability: Policies that promote sustainable economic growth, job creation, and wage increases that outpace inflation.
- Data-Driven Decisions: Utilizing advanced analytics to understand market dynamics and tailor policies to specific regional needs.
Conclusion: A Balanced Outlook for Housing Affordability 2026
The outlook for housing affordability 2026 is complex and multifaceted, characterized by both persistent challenges and potential opportunities. While high interest rates, limited supply, and inflationary pressures are likely to continue exerting upward pressure on housing costs, there are also factors that could offer some relief.
A potential stabilization or slight decrease in interest rates, coupled with increased housing supply through innovative construction methods and more permissive zoning, could gradually improve affordability. Furthermore, a sustained period of real wage growth would be a significant boon for prospective buyers.
However, the underlying structural issues – particularly the chronic undersupply of housing in many desirable areas and the widening gap between income growth and home price appreciation – will not disappear overnight. Addressing housing affordability 2026 effectively will require concerted efforts from all stakeholders: governments, developers, financial institutions, and communities.
For individuals, the journey to homeownership in 2026 will demand strategic planning, financial discipline, and a willingness to adapt to evolving market conditions. Staying informed about economic trends, understanding local market dynamics, and exploring all available resources will be crucial. While the path may be challenging, with careful navigation and proactive measures, the dream of homeownership can remain within reach for many.
Ultimately, the narrative of housing affordability 2026 will be written by the interplay of global economic forces, domestic policies, and individual choices. By acknowledging the complexities and working collaboratively, we can strive towards a future where housing is not just a commodity, but an accessible and stable foundation for all.