Master the 3-Month Rule: Build a $10,000 Emergency Fund by Mid-2026
Anúncios
Financial stability is not a luxury; it’s a necessity. In a world full of uncertainties, having a robust emergency fund can be the difference between weathering a storm and being capsized by it. The goal for many is to achieve a significant financial cushion, and for good reason. Today, we’re going to dive deep into a practical, actionable plan to build a substantial emergency fund of $10,000 by mid-2026, leveraging the powerful 3-Month Rule. This isn’t just about saving money; it’s about building a fortress of financial security that allows you to breathe easier, sleep better, and pursue your goals with confidence.
Anúncios
Many financial experts advocate for having at least three to six months’ worth of living expenses saved in an easily accessible account. This is the essence of the 3-Month Rule. For many, $10,000 represents a significant portion of those three months’ expenses, making it an excellent, tangible target. By breaking down this ambitious goal into manageable steps, you’ll discover that building an emergency fund of $10,000 is not just a dream, but an achievable reality.
This comprehensive guide will walk you through every step, from understanding the ‘why’ behind an emergency fund to implementing advanced saving strategies. We’ll cover budgeting techniques, income-boosting ideas, and how to stay motivated on your journey to financial freedom. By mid-2026, you could be celebrating a significant financial milestone – a fully funded $10,000 emergency fund. Let’s get started!
Anúncios
Understanding the ‘Why’: The Importance of an Emergency Fund
Before we delve into the ‘how,’ it’s crucial to solidify the ‘why.’ Why is it so important to build an emergency fund of $10,000? Life is unpredictable. Unexpected events can derail even the most carefully laid plans. These could include job loss, medical emergencies, car repairs, home maintenance issues, or even unforeseen travel. Without an emergency fund, these situations often lead to accumulating high-interest debt, depleting retirement savings, or making difficult financial choices that can have long-term negative impacts.
Protection Against Job Loss
One of the most common reasons people tap into their emergency savings is job loss. Finding a new job can take time, often several months. An emergency fund provides a crucial buffer, allowing you to cover your essential living expenses without panic or desperation. This financial cushion gives you the freedom to find the right job, rather than being forced to take the first available option out of necessity.
Covering Unexpected Medical Expenses
Health issues can arise without warning, and even with good insurance, out-of-pocket costs can be substantial. Deductibles, co-pays, and uncovered treatments can quickly add up. An emergency fund ensures that you can focus on your health and recovery, rather than worrying about how to pay the bills.
Handling Unforeseen Home and Car Repairs
Your home and car are significant assets, and they often require unexpected maintenance. A burst pipe, a broken appliance, or a major car repair can cost hundreds or even thousands of dollars. Having an emergency fund of $10,000 means these unexpected expenses won’t throw your entire budget into disarray or force you to put them on a credit card.
Peace of Mind and Reduced Stress
Perhaps the most invaluable benefit of an emergency fund is the peace of mind it provides. Knowing you have a financial safety net reduces stress and anxiety about the future. It allows you to make decisions from a position of strength, not fear. This psychological benefit alone is often worth the effort of building your fund.
The 3-Month Rule: Setting Your Target
The 3-Month Rule suggests having at least three months’ worth of essential living expenses saved. For some, this might be less than $10,000, for others, it might be more. However, $10,000 is a solid, achievable goal that provides a significant level of security for most individuals and families. To determine your exact target, calculate your essential monthly expenses (rent/mortgage, utilities, groceries, transportation, insurance, minimum debt payments). Multiply that by three to get your ideal 3-month target. If your essential expenses are, for example, $3,000 per month, then $9,000 would be your 3-month target, making $10,000 an even more robust goal.
Why Mid-2026?
Setting a specific deadline like mid-2026 (approximately 2.5 years from now, depending on when you start) makes the goal tangible and creates a sense of urgency. This timeframe allows for consistent, manageable contributions without feeling overwhelmed. It’s long enough to make significant progress, but short enough to keep you motivated.
Phase 1: Assessment and Budgeting (The Foundation)
The first step in building your emergency fund of $10,000 is to understand your current financial situation. You can’t effectively plan without knowing where your money is going.
1. Track Your Spending
For at least one month, meticulously track every single dollar you spend. Use a budgeting app, a spreadsheet, or even a notebook. This exercise reveals your spending habits and identifies areas where you can cut back. Many people are surprised to find how much they spend on non-essential items like dining out, subscriptions, or impulse purchases.
2. Create a Detailed Budget
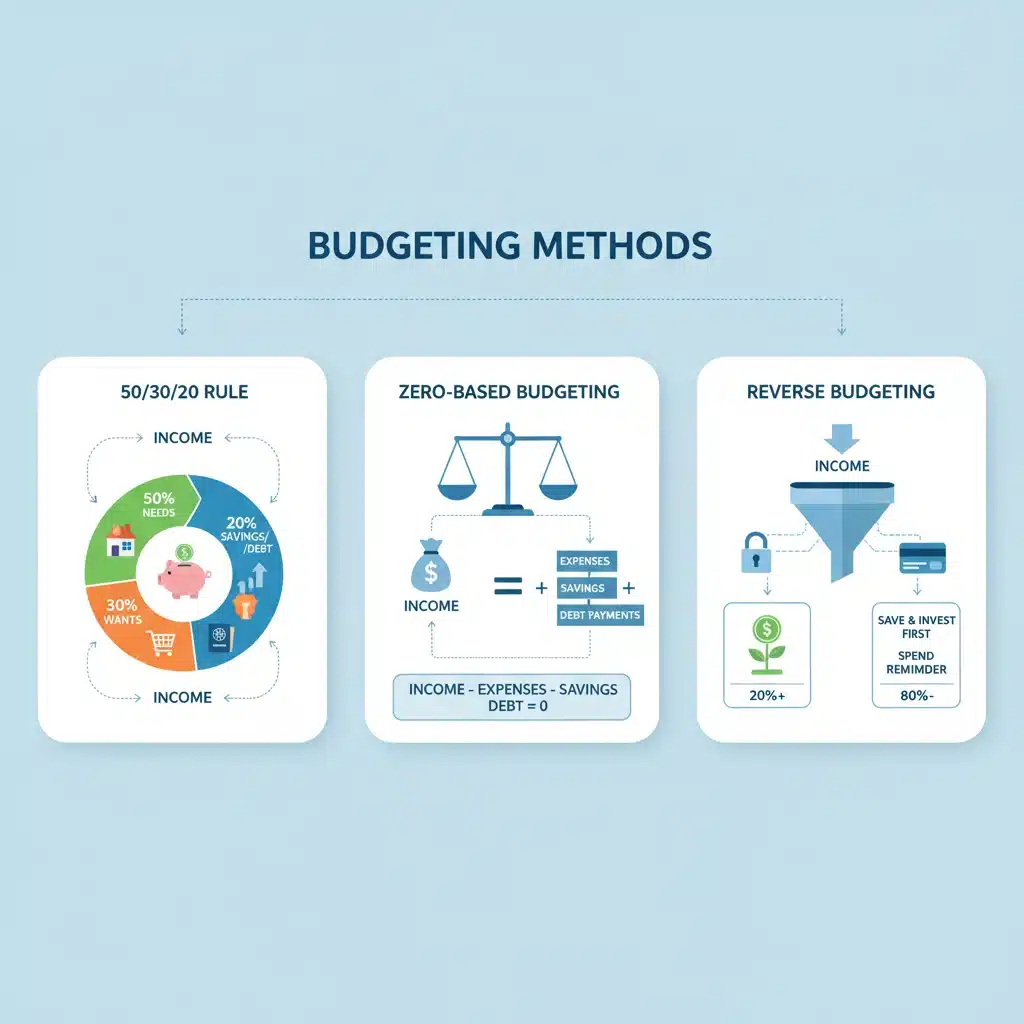
Once you know where your money is going, create a realistic budget. A budget isn’t about restriction; it’s about intentional spending. Allocate your income to different categories: housing, food, transportation, debt payments, savings, and discretionary spending. Popular budgeting methods include:
- The 50/30/20 Rule: 50% needs, 30% wants, 20% savings and debt repayment.
- Zero-Based Budgeting: Assign every dollar a job so your income minus expenses equals zero.
- Envelope System: Physically divide cash into envelopes for different spending categories.
The key is to find a method that works for you and that you can stick to consistently. Make sure your budget explicitly includes a line item for your emergency fund contributions.
3. Identify Areas for Cutting Expenses
Review your budget with a critical eye. Where can you realistically cut back? This might involve:
- Reducing Discretionary Spending: Less dining out, fewer impulse purchases, cheaper entertainment options.
- Negotiating Bills: Call your internet, cable, and insurance providers to see if you can get a better rate.
- Canceling Unused Subscriptions: Review all your monthly subscriptions and cancel those you don’t use regularly.
- Lowering Utility Costs: Be more mindful of energy consumption at home.
- Meal Prepping: Cooking at home is almost always cheaper than eating out.
Every dollar saved from expenses is a dollar that can go towards your emergency fund of $10,000.
Phase 2: Aggressive Saving Strategies (Accelerating Your Progress)
With a clear budget in place, it’s time to supercharge your savings efforts. This phase focuses on automating your savings and finding extra money.
1. Automate Your Savings
This is arguably the most important step. Set up an automatic transfer from your checking account to a separate savings account specifically for your emergency fund. Schedule this transfer to occur on your payday. Out of sight, out of mind – you’re less likely to spend money you don’t see in your primary account. Aim to contribute a consistent amount every month. To reach $10,000 by mid-2026 (approximately 30 months from late 2023), you’ll need to save roughly $333 per month. Adjust this based on your starting date and current financial situation.
2. Boost Your Income
If cutting expenses isn’t enough, or if you want to accelerate your progress, consider increasing your income. Here are some ideas:
- Side Hustles: Freelancing, ride-sharing, food delivery, pet sitting, online tutoring, selling crafts.
- Selling Unused Items: Declutter your home and sell items you no longer need on platforms like eBay, Facebook Marketplace, or local consignment shops.
- Asking for a Raise: If you’ve been performing well at your job, prepare a case for why you deserve a raise.
- Overtime: If available at your current job, picking up extra hours can significantly boost your income.
Dedicate any extra income directly to your emergency fund of $10,000. This can be a game-changer for reaching your goal faster.
3. Windfalls and Bonuses
Any unexpected money that comes your way – tax refunds, work bonuses, gifts, inheritance – should be primarily directed towards your emergency fund. Resist the urge to spend these windfalls; they are powerful accelerators for your savings goal.
4. Debt Reduction (Strategically)
While building an emergency fund, it’s important to also address high-interest debt. Some experts suggest having a small starter emergency fund (e.g., $1,000) first, then aggressively paying down high-interest debt, and then fully funding the emergency fund. This is because the interest you pay on credit card debt often far outweighs any interest you earn on savings. Evaluate your debt situation and create a plan that balances building your emergency fund with tackling high-interest liabilities.
Phase 3: Optimizing Your Emergency Fund (Where to Keep Your Money)
Once you start accumulating funds, where should you keep your emergency fund of $10,000? The key is accessibility and safety, not high returns.
1. High-Yield Savings Accounts (HYSAs)
The best place for your emergency fund is typically a high-yield savings account. These accounts offer significantly higher interest rates than traditional savings accounts, helping your money grow a little faster, while still being FDIC-insured and easily accessible. Look for accounts with no monthly fees and no minimum balance requirements.
2. Avoid Investments
Do not invest your emergency fund in the stock market or other volatile assets. The primary purpose of this money is safety and accessibility, not growth. You don’t want to be in a situation where you need the money, but the market has taken a downturn, forcing you to sell at a loss.
3. Keep it Separate
Ensure your emergency fund is in a separate account from your everyday checking account. This reduces the temptation to dip into it for non-emergencies. Some people even use a different bank for their emergency fund to create an extra layer of separation.
Phase 4: Staying Motivated and Overcoming Challenges
Building an emergency fund of $10,000 is a marathon, not a sprint. There will be times when you feel discouraged or tempted to spend your savings. Here’s how to stay on track:
1. Track Your Progress
Seeing your savings grow can be incredibly motivating. Use a spreadsheet, a visual tracker (like a thermometer chart), or your banking app to regularly check your balance. Celebrate small milestones along the way – hitting $1,000, $5,000, or halfway to your goal.
2. Set Realistic Expectations
There might be months where you can save more, and months where you save less. Life happens. Don’t get discouraged by setbacks. If you have an unexpected expense that forces you to dip into your fund, simply re-evaluate your budget and get back on track. The fund is there to be used in emergencies!
3. Find an Accountability Partner
Share your goal with a trusted friend or family member. Having someone to check in with can provide encouragement and help you stay accountable to your financial goals.
4. Reward Yourself (Responsibly)
When you hit significant milestones, allow yourself a small, non-financial reward. This could be a special meal cooked at home, a day trip, or a new book. Avoid rewards that derail your financial progress.
5. Revisit Your ‘Why’
When motivation wanes, remind yourself why you started this journey. Picture the peace of mind, the security, and the freedom that a fully funded emergency fund of $10,000 will bring. This mental reinforcement can be incredibly powerful.
Common Pitfalls to Avoid
As you work towards building your emergency fund, be aware of these common mistakes:
- Not Having a Separate Account: Keeping emergency funds in your checking account makes it too easy to spend.
- Using it for Non-Emergencies: A sale on a new TV or a spontaneous vacation are not emergencies. Stick to the definition!
- Not Replenishing After Use: If you use your emergency fund, make replenishing it your top financial priority.
- Ignoring Inflation: While not a primary concern for short-term savings, over very long periods, the purchasing power of your emergency fund can erode. However, for a 2.5-year goal, accessibility trumps inflation concerns.
- Getting Discouraged by Slow Progress: Every dollar saved is progress. Don’t compare your journey to others.
Beyond $10,000: What Comes Next?
Once you achieve your goal of building an emergency fund of $10,000 by mid-2026, congratulations! This is a massive accomplishment. But the financial journey doesn’t stop there. You might then consider:
- Increasing Your Emergency Fund: If $10,000 only covers 2 months of expenses, you might aim for 6 months, or even 12 months, especially if you have an unstable income.
- Investing for Retirement: Max out your 401(k), IRA, or other retirement accounts.
- Saving for Other Goals: A down payment on a house, a child’s education, a dream vacation.
- Paying Down Debt Aggressively: Tackle any remaining high-interest debt.
The habits you build while saving for your emergency fund – budgeting, tracking, disciplined saving – will serve you well for all future financial goals.
Conclusion: Your Path to Financial Security by Mid-2026
Building an emergency fund of $10,000 by mid-2026 is an ambitious yet entirely achievable goal. It requires commitment, discipline, and a clear plan. By understanding the importance of an emergency fund, creating a detailed budget, aggressively saving and boosting your income, optimizing where you keep your money, and staying motivated through challenges, you can transform your financial future.
Imagine the peace of mind you’ll feel knowing you have a robust financial safety net. No more financial anxiety during unexpected life events. This journey is about more than just money; it’s about empowerment, freedom, and building a more secure future for yourself and your loved ones. Start today, stay consistent, and by mid-2026, you’ll be celebrating a significant milestone on your path to true financial independence.