Car Loan Refinance 2026: Lower Payments & Save Money
Anúncios
In the ever-evolving financial landscape of 2026, finding ways to optimize your budget is more crucial than ever. For many, a significant portion of their monthly expenses goes towards car payments. If you’re looking to free up cash, lower your overall debt, or simply get a better deal on your auto financing, then understanding the ins and outs of a car loan refinance is paramount. This comprehensive guide will walk you through everything you need to know about refinancing your car loan in 2026, helping you potentially lower your monthly payment by 10% or even more.
Refinancing a car loan might sound complex, but it’s essentially taking out a new loan to pay off your existing one. The goal? To secure better terms, typically a lower interest rate, which translates to reduced monthly payments and significant savings over the life of the loan. With interest rates fluctuating and personal financial situations changing, 2026 could be the perfect year to re-evaluate your auto financing.
Anúncios
What is Car Loan Refinance and Why Consider It in 2026?
A car loan refinance involves replacing your current auto loan with a new one, usually from a different lender, but sometimes from the same one. The primary motivation for most people is to secure a lower annual percentage rate (APR), which directly impacts the total amount of interest paid and the size of your monthly payment. Other reasons include changing the loan term, which can either reduce monthly payments (by extending the term) or save on total interest (by shortening the term).
Anúncios
Why is 2026 a Good Time for a Car Loan Refinance?
- Evolving Interest Rates: Financial markets are dynamic. If interest rates have dropped since you first financed your car, you could qualify for a significantly lower rate now. Even a percentage point or two can translate to hundreds, if not thousands, of dollars in savings.
- Improved Credit Score: Has your credit score improved since you first bought your car? A higher credit score makes you a more attractive borrower, enabling you to qualify for better loan terms and lower interest rates. Lenders view borrowers with excellent credit as less risky.
- Changed Financial Situation: Perhaps you’ve received a promotion, paid off other debts, or simply have a more stable financial footing. These changes can make you eligible for more favorable loan conditions than when you initially took out your loan.
- Desire for Lower Monthly Payments: If your budget has tightened or you simply want more disposable income, extending your loan term through refinancing can reduce your monthly payments, making your budget more manageable.
- Getting Rid of Unfavorable Loan Terms: Maybe you rushed into your original loan, or it came with predatory terms. Refinancing offers a second chance to secure a fair and manageable loan.
Key Benefits of Refinancing Your Car Loan
The advantages of a successful car loan refinance are numerous and can significantly impact your financial well-being.
1. Lower Monthly Payments
This is often the most immediate and attractive benefit. By securing a lower interest rate or extending your loan term, your monthly outlay for your car can decrease, freeing up cash for other expenses, savings, or investments. For instance, if you’re currently paying $400 a month at 7% APR, refinancing to 4% APR could easily drop your payment by $30-$50, depending on your remaining term and principal.
2. Save Money on Interest Over Time
A lower interest rate means you pay less money to the lender over the life of the loan. This can add up to substantial savings. Even if your monthly payment reduction seems modest, the cumulative interest savings can be significant, especially on larger loan amounts or longer terms.
3. Shorten Your Loan Term (and Pay Less Interest)
If your financial situation has improved, you might be able to afford higher monthly payments. In this scenario, you could refinance to a shorter loan term at a lower interest rate. While your monthly payment might increase slightly, you’ll pay off the car faster and drastically reduce the total interest paid.
4. Remove a Co-signer
If you initially needed a co-signer due to your credit history, and your credit has since improved, refinancing can allow you to remove them from the loan. This frees them from their obligation and gives you full responsibility for the debt.
5. Access Cash with Cash-Out Refinance (Use with Caution)
Some lenders offer cash-out refinancing, where you borrow more than you owe on the car and receive the difference in cash. While this can provide quick funds, it also increases your debt and should be approached with extreme caution, ensuring you can comfortably repay the larger loan.
When is the Right Time to Refinance Your Car Loan?
Deciding when to pursue a car loan refinance is crucial for maximizing benefits. Here are key indicators that it might be the right time for you:
- Interest Rates Have Dropped: Keep an eye on general interest rate trends. If rates are lower than what you’re currently paying, it’s a good sign.
- Your Credit Score Has Improved: A jump in your credit score (e.g., from fair to good, or good to excellent) is a strong signal that you can qualify for better rates.
- You Have a High Interest Rate: If your current APR is significantly higher than the prevailing rates for similar loans (especially if it’s over 7-8% for a well-qualified borrower), refinancing is likely beneficial.
- Your Financial Situation Has Stabilized: A steady income and a low debt-to-income ratio make you a more attractive borrower.
- You’re Not Upside Down on Your Loan: It’s harder to refinance if you owe more on the car than it’s worth (negative equity). Lenders prefer to lend on assets worth more than the loan amount.
- Your Car is Not Too Old or Has Excessive Mileage: Most lenders have restrictions on the age and mileage of vehicles they will refinance. Typically, cars older than 7-10 years or with over 100,000-150,000 miles might be difficult to refinance.
Step-by-Step Guide to Car Loan Refinance in 2026
Navigating the refinancing process can be straightforward if you follow these steps:
Step 1: Gather Your Current Loan Information
Before you start shopping, know what you’re working with. You’ll need:
- Your current monthly payment
- Your current interest rate (APR)
- Your loan term (original and remaining)
- Your current loan balance (payoff amount)
- Your lender’s name and account number
- Vehicle information: Make, model, year, VIN, and current mileage
You can usually find this information on your monthly statement or by contacting your current lender.
Step 2: Check Your Credit Score and Report
Your credit score is the biggest factor determining the interest rate you’ll be offered. Obtain your free credit report from AnnualCreditReport.com and check your score. Look for any errors that could be dragging your score down and dispute them. A higher score means better refinance offers.
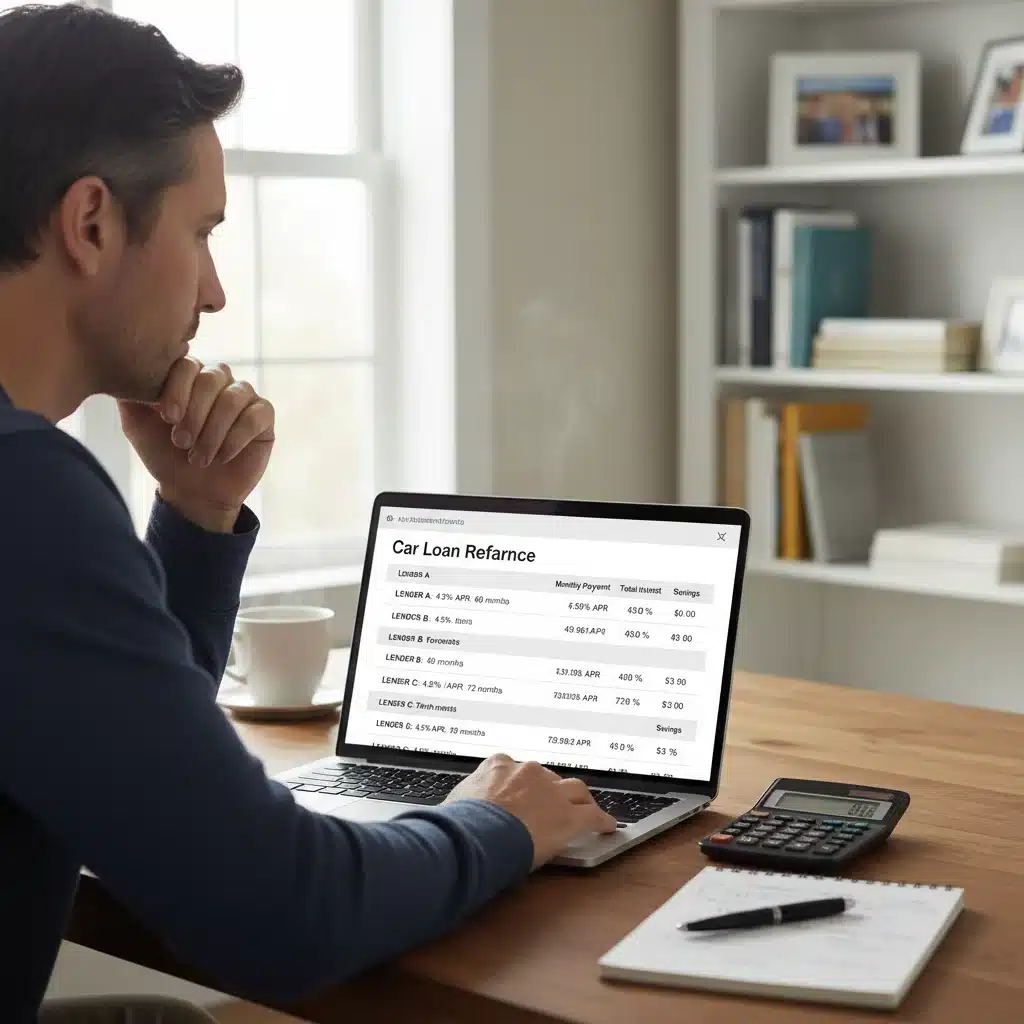
Step 3: Shop Around and Compare Offers
This is perhaps the most critical step. Don’t just go with the first offer you receive. Apply with multiple lenders, including:
- Banks: Large national banks and smaller local banks.
- Credit Unions: Often known for offering competitive rates and personalized service.
- Online Lenders: Many fintech companies specialize in auto refinancing and offer quick application processes and competitive rates.
When comparing offers, look beyond just the interest rate. Consider:
- APR vs. Interest Rate: APR includes fees, giving you a more accurate picture of the total cost.
- Loan Term: Does it meet your goals (lower payment or faster payoff)?
- Fees: Are there any application fees, origination fees, or prepayment penalties?
- Customer Service: Read reviews and check their reputation.
Step 4: Submit Your Application
Once you’ve chosen the best offer, you’ll need to formally apply. This typically involves:
- Providing personal information (name, address, Social Security number)
- Income verification (pay stubs, tax returns)
- Proof of residence
- Vehicle details (title, registration)
- Current loan details
Lenders will perform a hard credit inquiry, which may temporarily ding your credit score by a few points. However, applying with multiple auto lenders within a short period (usually 14-45 days, depending on the scoring model) will typically count as a single inquiry, so don’t be afraid to shop around.
Step 5: Finalize the Loan and Pay Off Your Old Loan
If approved, review the new loan documents carefully before signing. Ensure all terms match what you were offered. Once signed, the new lender will typically pay off your old loan directly. You’ll then begin making payments to your new lender under the new terms.
Potential Pitfalls and How to Avoid Them
While car loan refinance can be highly beneficial, there are some potential downsides to be aware of:
1. Extending the Loan Term Too Much
While extending your loan term lowers monthly payments, it also means you’ll pay interest for a longer period, potentially increasing the total cost of the loan. Aim for the shortest term you can comfortably afford.
2. Being Upside Down on Your Loan
If your car is worth less than what you owe, you have negative equity. Many lenders are hesitant to refinance loans with significant negative equity. You might need to make a down payment to cover the difference or wait until your car’s value catches up.
3. Prepayment Penalties
Some older or subprime auto loans may have prepayment penalties. Check your current loan agreement to see if you’ll be charged a fee for paying it off early. This fee could offset some of your refinancing savings.
4. Impact on Credit Score
A hard inquiry for a new loan can temporarily lower your credit score. However, if you consistently make your new payments on time, your score will recover and likely improve over the long term.
5. Refinancing Too Soon
If you’ve only had your current loan for a few months, refinancing might not yield significant savings, especially if you’ve already paid a substantial amount of interest upfront (due to amortization schedules where more interest is paid early in the loan).
Factors Affecting Your Car Loan Refinance Eligibility and Rates
Several elements play a role in whether you qualify for a car loan refinance and what rates you’ll receive:
- Credit Score: As mentioned, this is paramount. A higher score (700+) generally leads to the best rates.
- Debt-to-Income Ratio (DTI): Lenders look at how much of your gross monthly income goes towards debt payments. A lower DTI indicates you can handle more debt.
- Loan-to-Value Ratio (LTV): This compares your outstanding loan balance to your car’s current market value. Lenders prefer an LTV of 100% or less (meaning your car is worth at least what you owe).
- Vehicle Age and Mileage: Most lenders have limits. Newer cars with lower mileage are easier to refinance.
- Loan Amount: Some lenders have minimum and maximum loan amounts they are willing to refinance.
- Interest Rate Environment: General market interest rates will influence what lenders can offer.
What to Do if You’re Denied a Car Loan Refinance
If your application for a car loan refinance is denied, don’t despair. Request a reason for the denial from the lender. Common reasons include:
- Low credit score
- High debt-to-income ratio
- Negative equity (car worth less than loan)
- Vehicle too old or too many miles
- Insufficient income
Once you know the reason, you can work on improving that specific area:
- Improve Credit: Pay bills on time, reduce credit card balances, dispute errors.
- Reduce Debt: Pay down other loans or credit cards to lower your DTI.
- Build Equity: Make extra payments on your car loan to reduce the principal faster.
- Wait: Sometimes, waiting a few months for your credit to improve or for the car’s value to align better with the loan balance is the best strategy.
Conclusion: Take Control of Your Auto Financing in 2026
Refinancing your car loan in 2026 presents a significant opportunity to improve your financial health. By understanding the process, knowing when to act, and diligently shopping for the best rates, you can secure a lower interest rate, reduce your monthly payments, and save a substantial amount of money over the life of your loan. Don’t let an unfavorable original loan dictate your financial future. Take the initiative, explore your options, and take control of your auto financing today. Even a small reduction in your APR can lead to big savings, making your budget more flexible and your financial goals more attainable.